

LoanWise Calculator

- 11.00 Reviews
- 3.0
- Downloads
- 1,000,000+
Our take on LoanWise Calculator from Appgk
When I need a quick answer to “What would this loan cost me?” I usually do not want to open a full banking app, create an account, or sort through a spreadsheet. I want a small calculation that helps me decide whether it is worth making the next call. That is the space where LoanWise Calculator makes sense. It is a free finance app from Anuoluwapo Product Limited, focused on loan EMI estimates and deposit-interest calculations rather than trying to become a complete banking service.
I approached it as a practical decision tool, not as a replacement for a lender’s official quote. That distinction matters. A calculator can help me compare possibilities, spot an uncomfortable monthly payment, or estimate what savings might earn. It cannot turn an estimate into an approved offer, and it should not be treated as a contract. Used with that expectation, the app is straightforward and potentially useful.
The app is available to a broad audience, with an Everyone age rating, and it is free to install. Its current version is 1.8.0.0, and it requires Android 9 or later. That makes it a reasonable fit for people using a relatively recent Android phone, although anyone on an older device should check compatibility before planning around it. The product has passed the million-install mark, while its average rating sits at 3.0 from roughly 584 ratings, so I would describe its reception as mixed rather than universally enthusiastic.
From a vague money question to a usable estimate
Starting with the situation that actually matters
The most useful way to begin is with a specific question. For example, I might be considering a household purchase and wondering whether a proposed monthly payment is manageable. Instead of thinking only about the total amount borrowed, I can frame the problem around the loan amount, the interest rate, and the repayment period. Those inputs turn a general worry into something I can inspect.
Best Parts of LoanWise Calculator
Things to Keep in Mind About LoanWise Calculator
This is where a dedicated EMI calculator has an advantage over mental arithmetic. Monthly repayments are easy to underestimate, especially when a longer term makes the payment look comfortable while increasing the overall cost. LoanWise Calculator gives me a place to test that trade-off before I speak to a lender or accept a quote.
I also find the deposit side useful for a different starting condition. If I have money sitting in a savings or fixed-deposit product, the question changes from “Can I afford this payment?” to “What might this money earn?” A deposit-interest estimate can help me compare a proposed return with another option, provided I enter the terms consistently and remember that the result is only an estimate.
News and Features Related to LoanWise Calculator

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
Entering figures without losing the thread
The workflow is most effective when I prepare the figures first. I decide whether I am examining a loan or a deposit, gather the principal amount, and check the rate and period shown in the offer or account information. This small preparation step prevents a common mistake: entering a monthly rate where an annual rate is expected, or mixing months and years without noticing.
My practical advice is to write down the source of every number before entering it. If a lender says “interest from eight percent,” I would not silently assume that it is calculated in exactly the same way as the app’s formula. I would use the calculator to explore the scenario, then compare its result with the lender’s repayment schedule. The app is most valuable as a screening tool: it tells me whether a quote deserves closer attention.
Don't want to read the full review?
For a loan comparison, I would run the same amount through several repayment periods rather than changing everything at once. That isolates the effect of time. I might first keep the rate fixed and compare a shorter period with a longer one, then return to the preferred period and test a different rate. This two-pass method makes the result easier to understand than changing amount, rate, and term simultaneously.
Reading the result instead of chasing a single number
The monthly EMI is the number most people look for, but it is not the whole decision. I use it as a starting point, then ask what it implies over the full repayment period. A payment that looks acceptable in isolation may become expensive when repeated for many months. Conversely, a shorter term may produce a heavier monthly commitment but reduce the time I remain tied to the loan.
Screenshots
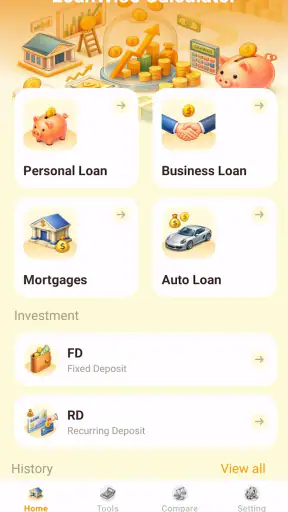
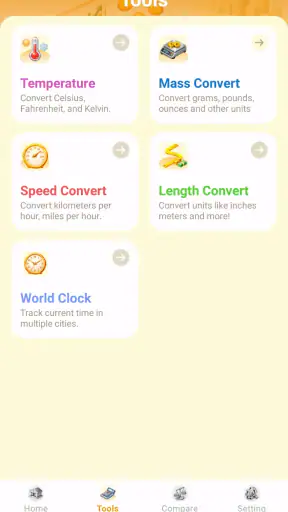
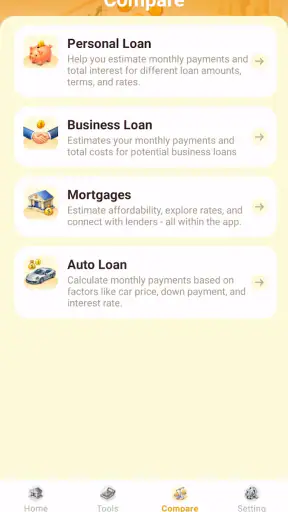
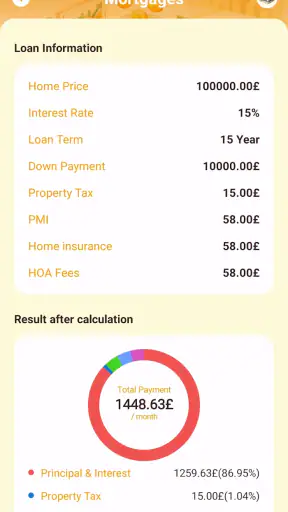
That is one of the app’s strongest practical roles: it helps turn a sales conversation into a comparison. If someone presents me with one monthly figure, I can test how that figure changes when the term or rate changes. I am not relying on the app to tell me what to choose; I am using it to expose the consequences of the choice.
On the deposit side, I would pay attention to whether the displayed interest is being considered as a simple estimate or as part of a compounding arrangement. The result should be checked against the account’s actual rules, including how often interest is credited and whether withdrawals affect the balance. A calculator output can be mathematically tidy while the real product has conditions that alter the final return.
Handoffs between the app and the real decision
The most important handoff happens after the calculation. I take the result out of the app and compare it with the document, message, or conversation that gave me the original figures. This is where I look for processing charges, insurance, taxes, late-payment consequences, variable rates, or a different repayment method. A clean EMI estimate does not automatically include those items.
For a family decision, I would share the assumptions as well as the result. Saying “the payment is this much” is less useful than saying “this is based on this amount, this rate, and this period.” That makes it easier for another person to reproduce the calculation and notice if one of the inputs is wrong. It also prevents the app’s output from becoming a misleading headline detached from its conditions.
For a small business owner, the handoff may be even more important. A loan payment has to fit alongside rent, wages, stock purchases, and irregular income. I would use the estimate to create a conservative planning figure, not the most optimistic one. If the business can only manage the payment when every month goes perfectly, the calculation has already revealed a risk that deserves attention.
Where the workflow is genuinely convenient
The app’s narrow focus is a benefit when I need speed. I am not looking for budgeting categories, investment research, bill reminders, or account aggregation. I want to estimate a loan payment or deposit return and move on. A focused calculator can be less distracting than a large financial platform filled with tools I will not use for this particular question.
It is also useful during early comparison. Before I contact several lenders, I can test a few realistic scenarios and discard options that are clearly outside my comfort zone. That saves time and gives me better questions to ask. Instead of asking only for the monthly payment, I can ask how the lender arrived at it and what extra charges sit outside the advertised figure.
Another less obvious use is checking whether a quoted payment seems plausible. If the lender’s number differs sharply from my estimate, that does not automatically mean the lender is wrong. It may indicate a different interest convention, fees rolled into the principal, or a different repayment structure. The discrepancy is a prompt to investigate, which is more valuable than blindly trusting either number.
Where the flow breaks down
The first limitation is the gap between an estimate and a real financial product. Loan terms are not always presented in a way that maps neatly to a simple calculator. Some products use reducing-balance interest, some advertise a flat rate, and some add charges at different points in the process. If I do not understand the lender’s method, I can enter accurate-looking figures and still get a comparison that is not like-for-like.
That means I would not use the app as the final authority for a major borrowing decision. For a mortgage, a large business loan, or any agreement with complicated fees, an official amortization schedule and written disclosure are more important. The calculator can help me prepare, but it should not replace professional advice or the lender’s binding documents.
The deposit calculation has a similar boundary. The app can help me estimate interest from the terms I enter, but the actual return may depend on compounding, withholding, minimum balances, early withdrawal rules, or changing rates. I would treat the displayed figure as a planning aid and verify the account conditions separately before moving money.
The mixed rating also affects my expectations. With an average of 3.0 from 584 ratings and only a small number of written reviews, I would install it with a little caution rather than assuming every experience will be smooth. That does not make it unusable, but it does reinforce the need to check each result and avoid entering sensitive information unless the app clearly requires it for a function I understand. For a simple calculator, I prefer the workflow to remain simple and transparent.
Who should use it, and who should choose something else
I think LoanWise Calculator is best for someone who wants a quick first estimate before comparing loan offers or deposit options. It suits a student planning a modest borrowing decision, a household checking whether a proposed payment fits its monthly budget, or a saver trying to understand the rough effect of a stated interest rate. It is also a sensible companion during a phone call with a lender, when I want to test an alternative term immediately.
I would be more hesitant to recommend it to someone who needs a full financial picture. If the real question involves debt payoff strategy, irregular income, multiple cards, investments, taxes, or long-term budgeting, a dedicated personal-finance app or spreadsheet will usually be better. Those tools can show cash flow and competing obligations, while this app is centered on individual calculations.
I would also choose a lender-provided calculator when I already know the exact product I am considering. A bank’s tool may reflect its own fees, repayment conventions, and eligibility rules more closely. LoanWise Calculator is more useful before that stage, when I am comparing broad scenarios and need an independent second look.
Three habits that make the estimates more useful
First, I would save the assumptions outside the app. A screenshot or written note containing the amount, rate, period, and date of the quote gives the result context. Without those details, an old estimate can easily be mistaken for a current offer. This is particularly important when rates change or when I compare different lenders over several conversations.
Second, I would test a less comfortable scenario rather than only the advertised one. If the rate increases, income falls, or the repayment period changes, does the plan still work? The point is not to predict the future perfectly. It is to discover whether the decision is fragile. A calculator becomes much more valuable when I use it to find the boundary at which the payment stops being manageable.
Third, I would separate affordability from cost. A longer term may solve the immediate monthly-pressure problem while increasing the total amount paid. A shorter term may be cheaper overall but difficult during a month with unexpected expenses. I would use the app to view both sides of that trade-off, then choose based on my actual cash flow rather than the smallest displayed EMI.
My final take after following the full workflow
LoanWise Calculator is a focused, free finance utility that does one small job in a useful way: it helps me turn loan and deposit questions into quick estimates. I like it most at the beginning of a decision, before paperwork and sales language make the options feel more complicated. Its value comes from comparison, not from pretending to provide a final financial answer.
The app’s limitations are important but manageable. I have to understand the figures I enter, check whether the lender uses the same calculation method, and look beyond the result for fees and account conditions. Its moderate average rating means I would keep my expectations practical, and I would verify important outputs rather than treating them as guaranteed figures.
For a simple “can I afford this roughly?” or “what might this deposit earn?” question, I would recommend giving it a try on a compatible Android device. For complex borrowing, detailed budgeting, or a final contract decision, I would pair it with the lender’s official schedule or choose a more comprehensive financial tool. My recommendation is to use it as a clear first checkpoint, not as the last word on your money.
LoanWise Calculator FAQ
What is LoanWise Calculator used for?
LoanWise Calculator is designed to help users estimate loan payments and understand borrowing costs before applying for credit. You can typically enter details such as the loan amount, interest rate, repayment period, and payment frequency to receive an estimated installment. It is useful for comparing scenarios, planning a budget, and checking whether a potential loan may fit your finances.
Can LoanWise Calculator guarantee the exact payment or loan approval I will receive?
No. LoanWise Calculator provides estimates rather than guaranteed offers. The final payment, interest rate, fees, and approval decision depend on the lender, your credit profile, income, loan type, and other conditions. Results may also vary if the app does not include taxes, insurance, origination charges, late fees, or other costs. Always confirm the complete terms directly with the lender.
What information do I need to use LoanWise Calculator?
Most calculations require the principal amount, annual interest rate, and loan term. Depending on the calculation mode, you may also need to select monthly or another payment frequency, enter a down payment, or include additional fees. The more accurate the information you provide, the more useful the estimate will be. Avoid entering sensitive personal or banking details unless the app specifically requires them.
Does LoanWise Calculator support different types of loans?
LoanWise Calculator may be useful for comparing common borrowing situations such as personal loans, auto financing, mortgages, or other installment loans, provided the relevant inputs are available. However, each loan product can use different rules, fees, compounding methods, and repayment structures. Before relying on a result, check whether the calculator supports the specific loan type and calculation method you need.
Is LoanWise Calculator safe to use, and should I rely on its results for financial decisions?
A loan calculator is generally a low-risk tool when used only for estimates, but you should still review the app’s privacy policy, permissions, developer information, and data-handling practices before installing it. Treat every result as educational guidance, not financial advice. Compare the estimate with official lender documents, account for your complete budget, and consult a qualified financial professional for important borrowing decisions.











